PBOC Plans Metrics to Limit Banks’ Long-Bond Holdings
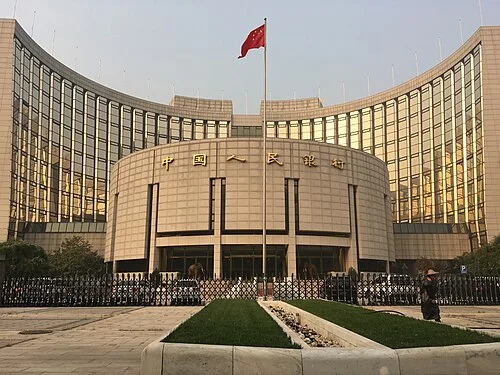
China’s central bank plans to consider adding new indicators to its Macro Prudential Assessment framework to curb banks’ growing exposure to long-dated government bonds and bond funds. The proposed measures would also monitor divergences between money-market rates and bond yields, which can encourage risky carry trades and leave banks vulnerable to losses if interest rates rise. The benchmarks and thresholds remain under discussion with financial institutions and would undergo consultation before being finalized. The initiative follows a strong rally in China’s bond market, driven partly by weak economic data and expectations of additional policy support; the 10-year government bond yield recently stood near 1.68%, close to its lowest level since July 2025. Market participants expect some smaller banks could exceed eventual limits on bond duration and fund holdings, forcing them to adjust their portfolios. The changes would expand the PBOC’s 2016 MPA framework, a key component of China’s dual monetary and macroprudential regulatory system.
Where do you stand?